Tuesday, August 25, 2020

Have you planned for your death?

What will happen to my money when I die?
If I'm involved in a serious accident, what will happen to me?
Will my family be burdened with paying my funeral costs?
What will my legacy be?

Have you planned for your death?

I have, and here's what I did:

"It's not about me. It's not about you. It's not even about us.
It's about legacy. It's about what we choose to leave behind for future generations."

Well-said, Mr. Stark!

I may not be doing anything as awesome as building a flying metal suit of armor powered by an exotic self-sustaining power source, but I can still establish a legacy. I can still plan to leave something behind for future generations.

To leave the decisions to some random judge or lawyer would be to put my legacy in jeopardy. That's why, despite being in my upper-20s and in perfect health, I've created a will.

In fact, I've created 3:

Tuesday, August 18, 2020

Links for August 2020

I don't normally watch a ton of YouTube videos, because there are too many time-wasters out there. But this video made a ton of great points about money, capitalism, and time.
    https://www.youtube.com/watch?v=6mRbDEtDoyA
*I'd note that the person who made this video missed one crucial element: risk tolerance. Sure, everything he says makes sense. But it doesn't make sense for just anyone to start a business. And he missed that crucial element.

Remember when everybody was panic-buying toilet paper and paper towels? This analysis provides some insight into why:

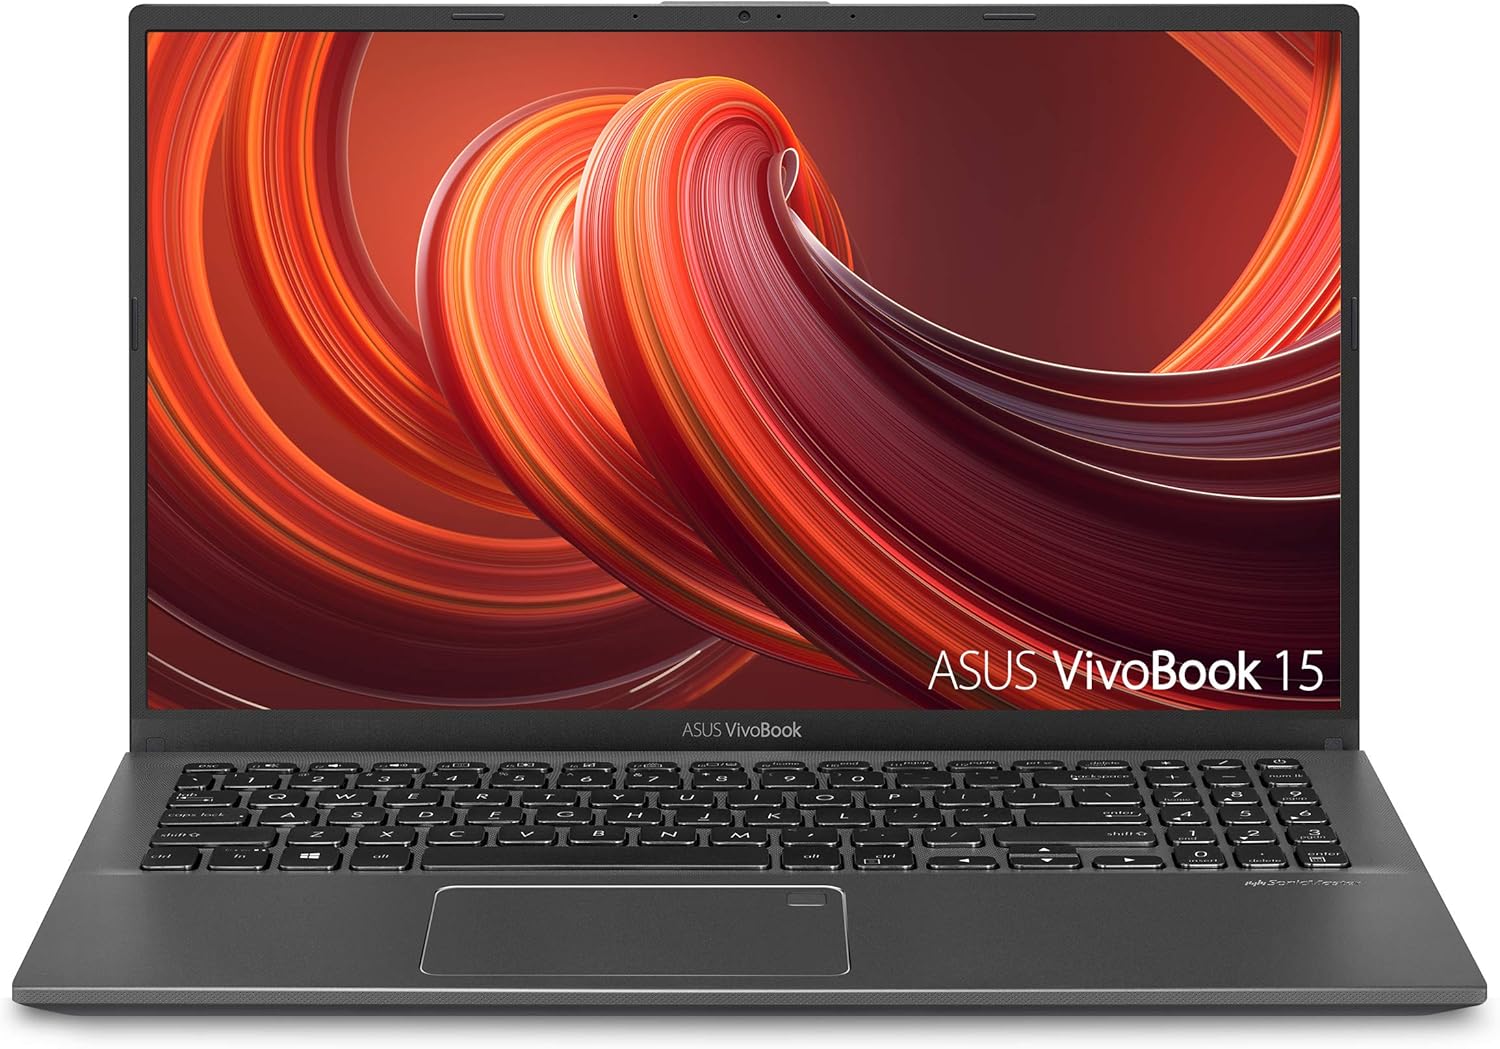
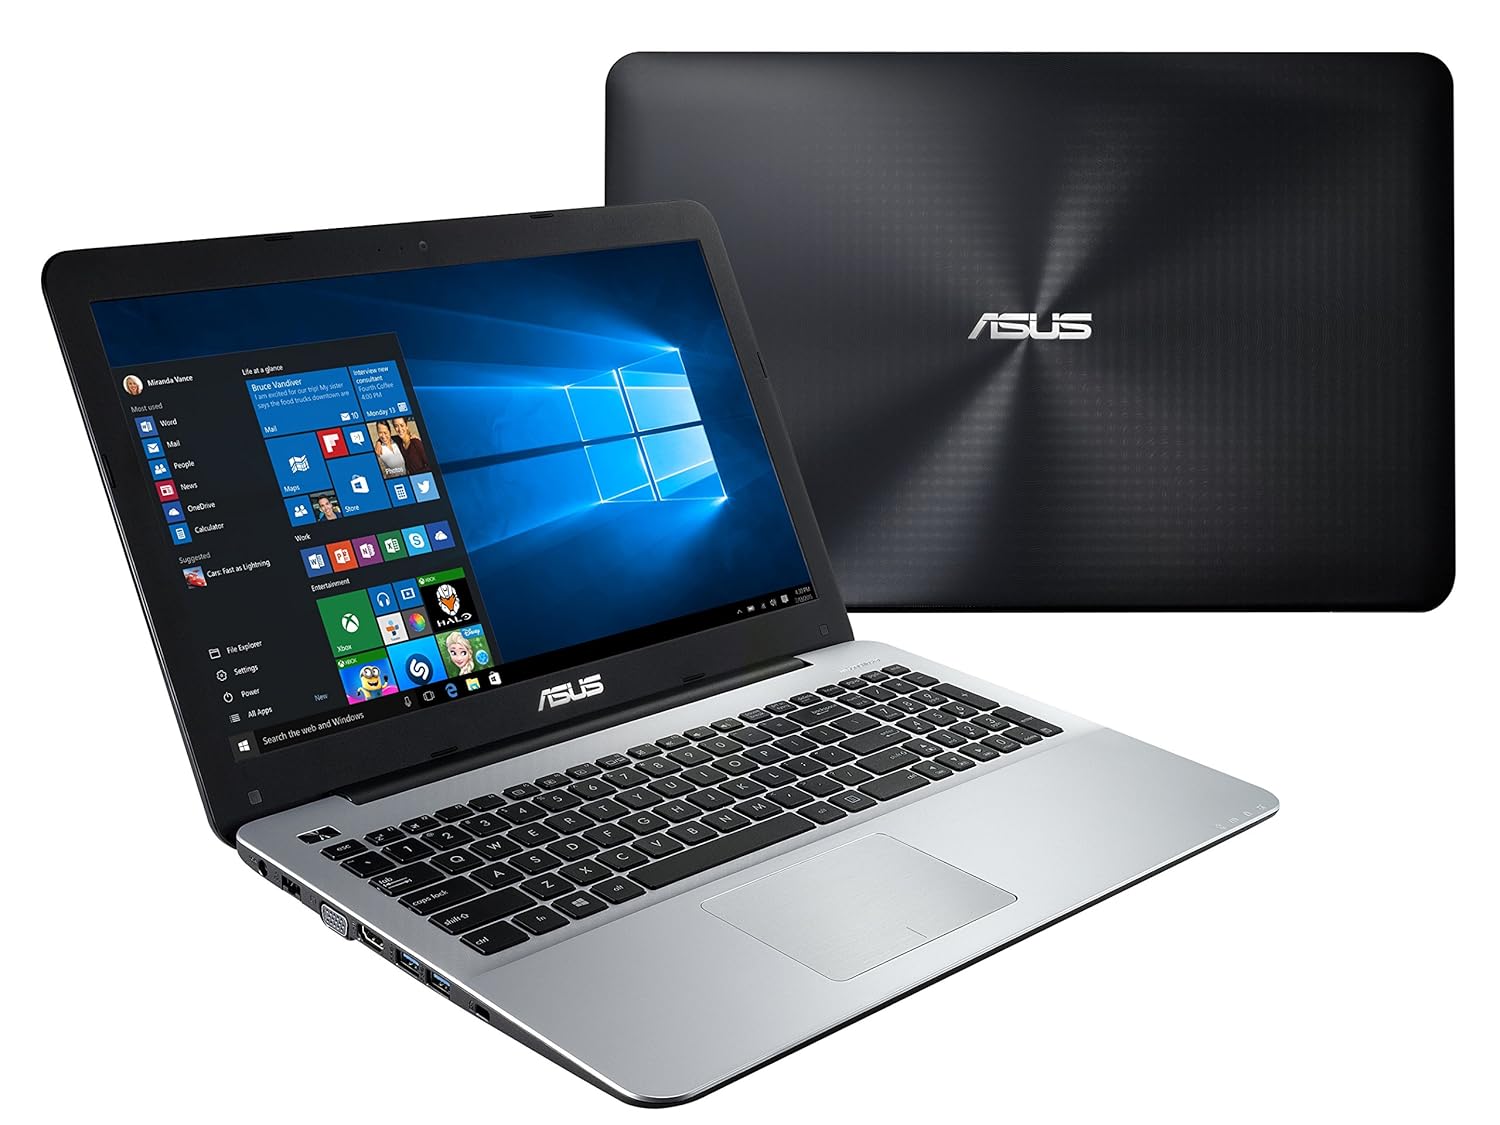
ASUS Vivobook 15 - $499
*A little light on the storage space, but it's pretty powerful for the price, and there are a number of options for extra storage.


Laws like this are exceedingly scary for homeowners:

How rich are Americans, by age group? 

Hey Americans, interested in what happens to your tax money? You might be surprised where the military ranks in this list...

A snapshot into the financial picture of "John," someone who retired in 2018 and is looking for income:

Tips to help you retire, regardless of what the economy is doing at the moment:


Steve Adcock and his wife retired early, in their thirties. He offers some advice to help the rest of us retire, as well:

Along similar lines as the above:

For some perspective on the REAL point of having money:

This post makes an important point about the power of emotions:

Scared to invest? Don't be. Here's why:

The best Vanguard funds:

Be on guard against financial abuse:

Entrepreneurship isn't necessarily all it's cracked up to be:

Possibly the single most succinct summary of the FIRE movement:

How much money do Americans think it takes to be financially comfortable? And how has COVID-19 changed that?

How should you invest? Ty of CampF.I.R.E. Finance describes one solid approach—index and chill:

Sunday, August 2, 2020

How Rich are Americans, by Age Group?

How Rich are Americans, by Age Group?

In September 2017, the U.S. Federal Reserve issued a report based on the Survey of Consumer Finances. This survey was based on 6254 families, and the Federal Reserve report broke down the data by age group.

Note that this survey includes a house as part of a household's assets; page 14 of the report specifies "Declines in house prices in particular had a disproportionate effect on families in the middle of the net worth distribution, whose wealth portfolio is dominated by housing."

I've created a graph to illustrate this information, using LibreOffice Calc, a free and open alternative to Microsoft Excel. Here's the graph:

Tuesday, July 7, 2020

The Two Components of Investing

 The Two Components of Investing

Investing is comprised of two parts:
  1. MATH.
    Do your research. Learn about the market. Learn what the overall market does, and when. Try to find out why—not necessarily why it went up or down on a given date, but what powers the market to begin with.


Thursday, May 14, 2020

Blog roundup May 2020

Blog roundup/interesting links May 2020

A great summary of the FIRE movement:
https://www.thousandaire.com/its-all-about-creating-income/

I've linked this before, but it's worth including again:
https://www.wealthwelldone.com/how-can-i-change-my-life/
     -And while we're using allegorical stories:
     https://froogalstoodent.blogspot.com/2017/01/a-tale-of-two-kingdoms.html

A sound planning session with Inspire to FIRE:
https://www.inspiretofire.com/recession-investment-plan/

The benefits of FI:
https://www.physicianonfire.com/the-benefits-of-financial-independence

Though I don't usually condone day trading, a little information about good, debt-free companies won't hurt. To that end, this is one part of a series on debt-free companies. I like the analysis, though it's not actually influencing my own investing decisions:
https://seekingalpha.com/article/4339254-debt-free-companies-of-s-and-p-500-jack-henry-associates

Some good guidance on how to handle a dip in the stock market if you're planning to retire soon; good advice to hear if you're worried about how the COVID-19 economic slowdown will affect your ability to retire:
https://www.moneytalksnews.com/retire-even-when-the-economy-heads-south/

Jim Collins is ALWAYS worth reading and considering. This one is particularly notable for a great line by Jon Older, in his 8:54 PM comment: "Like a famous person once said, money is like a bar of soap. The more you handle it, the smaller it gets." Great stuff!

How does Japan deal with its extreme population density, especially in Tokyo? Micro-apartments!

Another dose of sanity, this time from Mr. Money Mustache:
-The money quote: "But in this situation, it really helps to understand the big picture of what is actually going on. The world is not ending. The air outside your windows is not a swirling cloud of certain death. All that has changed is that we are in a self-imposed economic slowdown that has been created purely to save the lives of our most vulnerable people. Which is one of the most compassionate things our society has ever done." [emphasis in original]
Interested in earning cash for taking surveys and providing companies with feedback on their products and services? One option is https://www.inboxdollars.com/, which is currently offering a $5 signup bonus!

Wednesday, May 13, 2020

Are Roth IRAs a rip-off?

Roth IRAs vs. traditional IRAs—What's the advantage?

A while back, I had a brief debate with Financial Samurai in the comment section of one of his articles. His position was that Roth IRAs are a rip-off. I disagreed.

I like Financial Samurai, and he has a ton of great info on his website! But sometimes, two people see things differentlythe classic "reasonable people may disagree" argument. I believe that's what's happening here.


List, Demolition, Spiral Notebook, Rip, Torn, Tear

So I'll try to explain why I hold my position on the matter, using extensive quotes from the original page at https://www.financialsamurai.com/disadvantages-of-the-roth-ira-not-all-is-what-it-seems/#comment-343071

Sam: "So you think the government sucks, and you don't count on SS benefits, yet you are willing to pay more taxes up front? I don't understand the inconsistency."

Me: "There is no inconsistency."

Roth IRAs aren't a scheme to take your money. They simply give you the option to pay taxes now, or pay them later. Let me spell it out:

"You think the gov. is awful with money? [It is.] -> The gov. is going to have to pay the piper eventually. Since the gov. gets its money from taxes, that means that tax rates will be raised on everyone, across the board. I'm not talking 2019, or 2022, or 2025. I'm talking 2040 or 2050.

"If, like some people, you plan to 'work'—generate income—for as long as possible, you might well be in a higher income bracket AFTER "retirement" than you were at the beginning of your career."

-Financial Advice for Young Professionals illustrates the mathematical equivalence between a Roth IRA and a Traditional IRA, with the comment shown below:


Let’s say you’re in the 25% tax bracket. If you contribute 5,000 to a Roth IRA that is the same as contributing $6,666,67(not $5k) to a 401k. So after 10 years, both get a 5% return.
Roth: 5000*(1+.05)^10 = 8,144.47
401k: 6,666.67(1+.05)^10 = $10,859.30*(1-.25) = 8,144.47
The amounts are exactly the same after the 401k is taxed 25%. Now where I argue for a Roth is that how do you know what this 25% will go up or down. There are two factors that affect this: gov. tax rates and your future income. Both of which I guarantee you cannot predict with 100% certainty. And when you can’t predict something with certainty, I like to diversify. Which is what a Roth IRA does.
What if Sam has 3 kids and they each have 3 kids and now he has 9 grandchildren living in CA? Would he trade being away from his family for saving 10% on taxes? Hard to say :)
Me: "So, bottom line:

1) You pay the taxes now, and let that money grow. Once you're 59 and 1/2 years old, you can take the money out tax-free.

OR

2) You invest now, pre-tax, and pray that the gov. doesn't raise taxes on withdrawals 30 years in the future, or that your tax bracket in retirement is lower than your tax bracket is right now.

"Either way, you're still paying taxes on the investments in your IRA! Choosing option 1) amounts to a bet that you'll live to at least 60 years old, you won't need the money before then, and that the government will eventually have to raise taxes to bail it out of its own foolhardiness.

"Option 1) gives you certainty: you KNOW how much tax you'll pay. In 2060, I have no idea how much tax I'll pay on my forced distributions from a Traditional IRA, 401(k), etc! So Option 2) is less desirable from that standpoint.

If you pay 25% in taxes now, and you think you'll have to pay MORE than 25% in taxes in 2060, then choose a Roth IRA.

If you pay 25% in taxes now, and think you'll have to pay LESS than 25% in taxes in 2060, choose a traditional IRA."

So, to wrap things up:

Basically, whether you prefer a Roth IRA or a traditional IRA depends on what you expect the government to do regarding taxes in the future.

  • A traditional IRA means you expect your taxes to be lower in the future (either because your income will be reduced or because the government will lower your tax rate). Therefore, with this assumption, you'd rather pay later.
     
  • A Roth IRA means you expect your tax rate to be higher in the future, so you'd rather pay now.
So are Roth IRAs a rip-off? As Betteridge's Law suggests, the answer is "no." Whichever option you prefer depends on your situation. Choose wisely!


***
Support the Froogal Stoodent blog by checking out these laptops or these headphones;
anything you buy will generate a small commissionat no cost to you! Thanks!

Saturday, April 4, 2020

The Best Dollar Store

The Best Dollar Store

When it comes to low-price general stores, I've found that Dollar Tree is the best. Everything there truly is $1 or less!
    • However, not everything at Dollar Tree is a good deal. For example, most of their food is overpriced compared to grocery stores—yeah, it's only a dollar, but the special small package means that Dollar Tree food often costs more per ounce than a similar product at a grocery store.
       
    • For things like personal care items, decorations, Halloween costumes, microwavable plastic bowls, greeting cards, toys, etc., I really like Dollar Tree. For such items, durability isn't super-important, so Dollar Tree is a great low-cost, one-stop shop!
       
    • If you need durable or high-quality products—especially electronicslook elsewhere. But Dollar Tree is a great source for everything from security envelopes to coloring books for kids, especially if you just want something inexpensive.
       
    • I've been to Family Dollar, which is owned by Dollar Tree, according to the Bloomberg article above. Not impressed. Many of their products are ridiculously overpriced, and they aren't actually $1 (as the name implies)...the one time I went into Family Dollar to look around, I saw products that cost $8 or $10—products that I could have found elsewhere for less!
       
    • Dollar General is a similar story. Not a great deal on many of their products.
So, in sum, Dollar Tree is the king of the dollar stores. Long live the king!

***
Support the Froogal Stoodent blog by checking out these laptops or these headphones;
anything you buy will generate a small commissionat no cost to you! Thanks!

Saturday, February 22, 2020

Interesting links

Interested in football? In XFL 2020? In the entertainment industry? This is a quick but interesting read:
https://finance.yahoo.com/news/xfl-may-pull-off-something-no-league-has-before-but-week-3-is-critical-175105240.html


Interested in cars? In Australia? After 150 years, Holden is going away. This is probably surprising news, unless you live in Australia or work in the automotive industry:
https://www.autoweek.com/news/industry-news/a31023811/saving-holden-would-have-required-billions-report-says/

The human body apparently isn't 98.6 degrees anymore:
https://elemental.medium.com/the-average-human-body-temperature-is-no-longer-98-6-f-c88c19716852

A way to calculate retirement age in each state. Keep in mind that each person's situation is different, but this is a good way for us FIRE enthusiasts to stay focused on the end goal:
https://finance.yahoo.com/news/most-realistic-retirement-age-every-100000297.html

Tips on how to save for the down payment on a home, directed especially at first-time homebuyers:
https://www.thepennyhoarder.com/home-buying/how-to-save-for-a-down-payment/

Ideas for passive income, the holy grail for investors:
https://moneydoneright.com/best-passive-income-ideas/

Do you have to work until full retirement? Not if you don't want to:
https://www.forbes.com/sites/ryanderousseau/2020/03/27/32-year-old-stopped-focusing-early-retirement-embrace-mini-ones/#5a7d0fe3420b

Which should I prioritize: my emergency fund, or my retirement? https://www.thebalance.com/average-retirement-savings-by-age-4155888

Saturday, October 5, 2019

Best laptop bargains 2019

Best laptop bargains

Here are 2019's best laptop bargains, hand-picked by The Froogal Stoodent!

You'll find everything from general-purpose to gaming laptops (but mostly general-purpose). The sweet spot is usually $400-500 for a good, reliable machine that will get the job done.

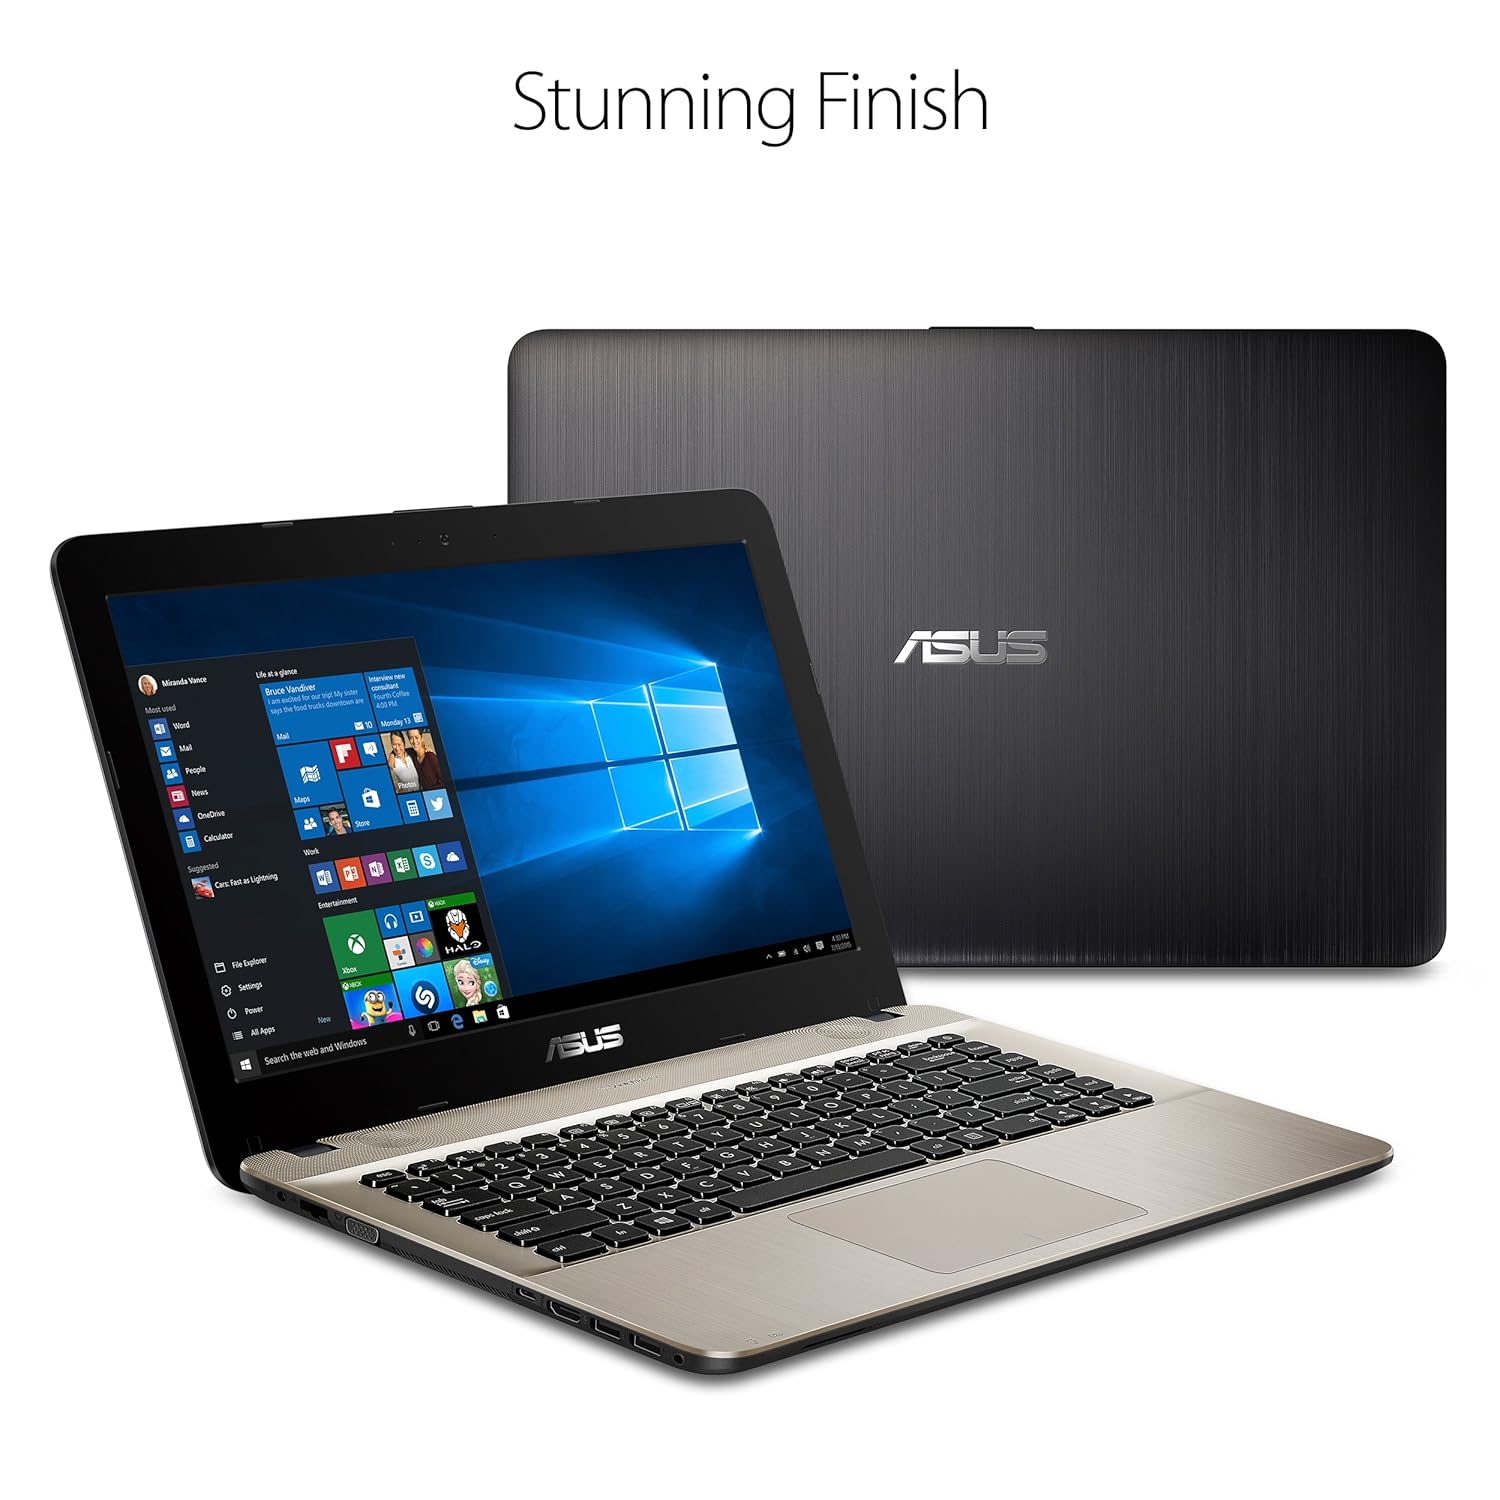
ASUS Vivobook F441 - $440
Amazon


  • 8 GB of the latest DDR4 RAM 
  • AMD A9-9425 processor 
  • 256 GB solid-state drive (SSD) version highly recommended

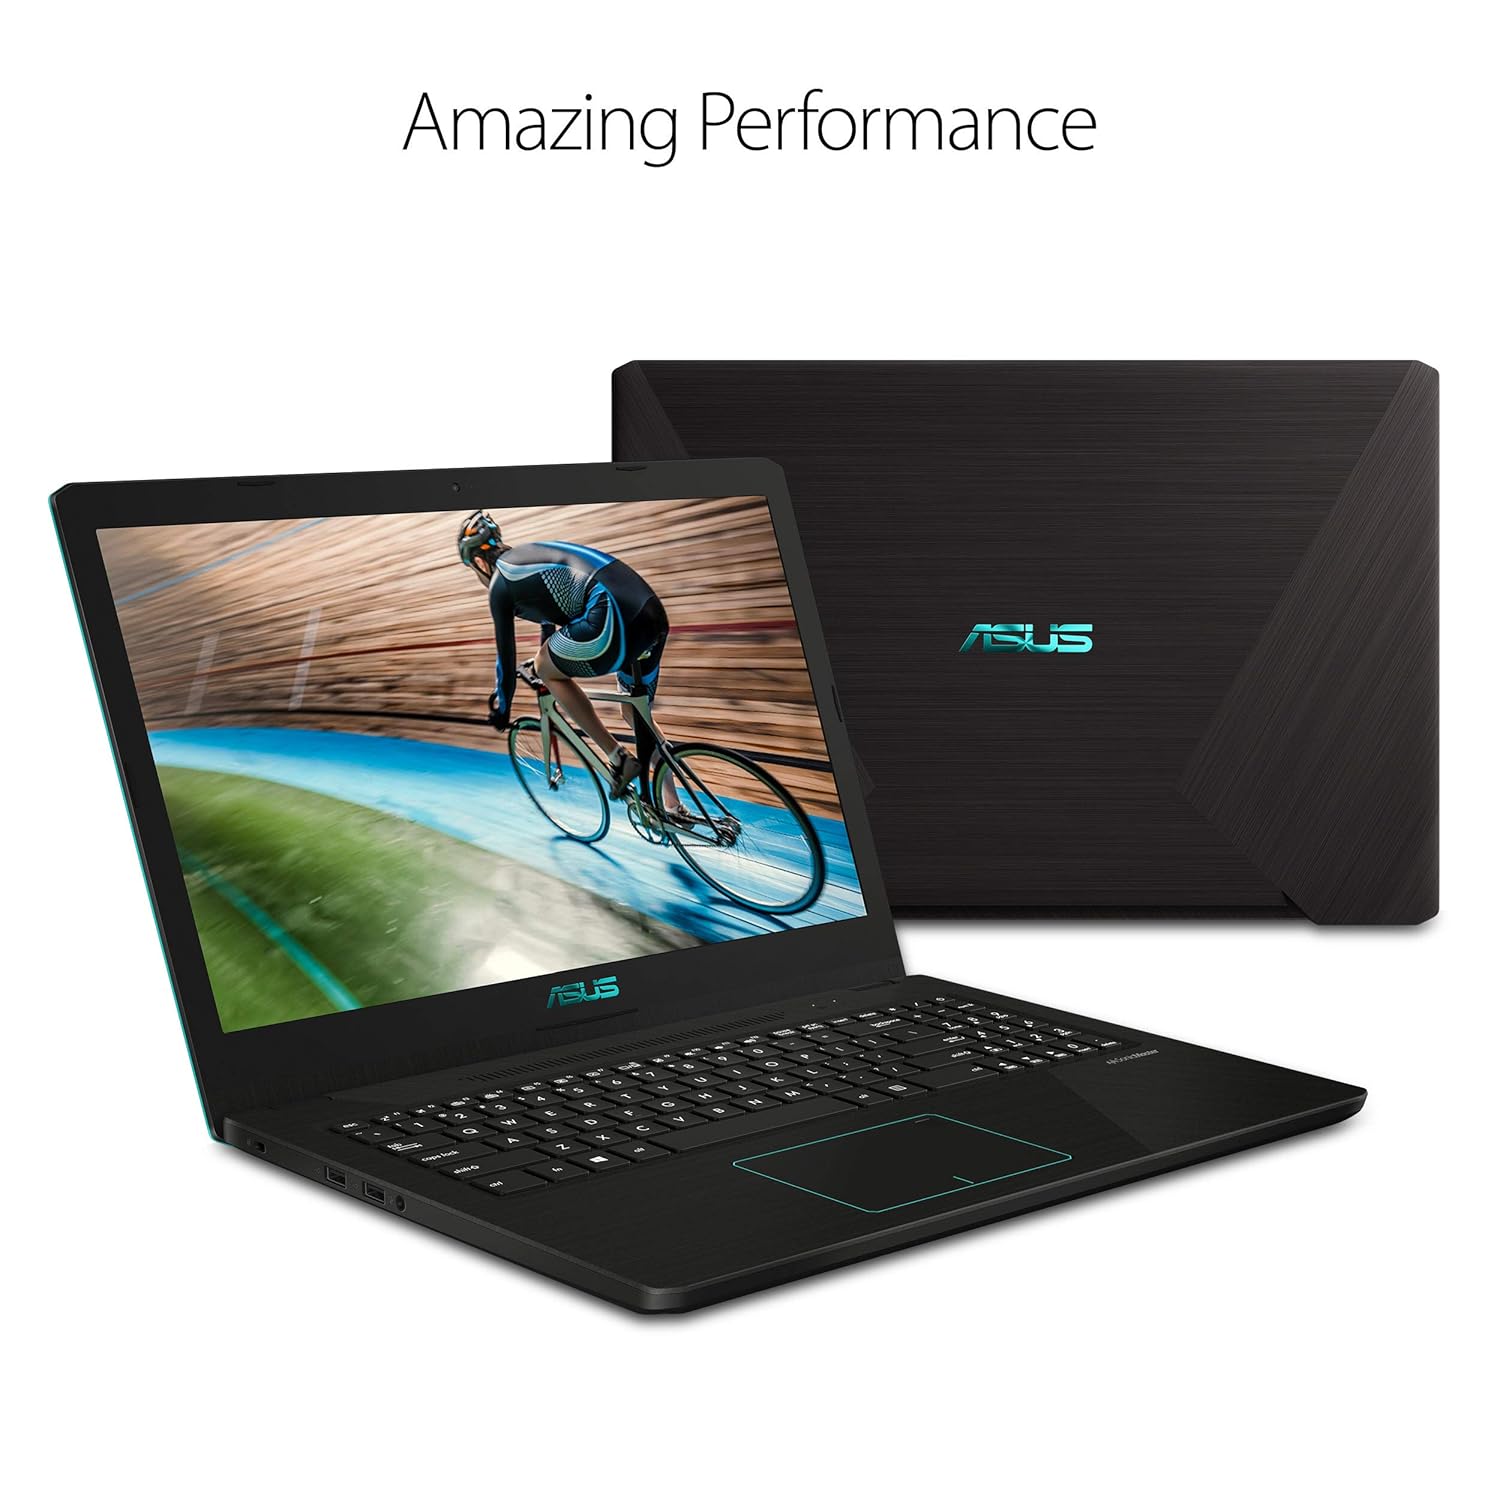
ASUS Vivobook K570ZD - $650
Amazon
  • 8 GB of DDR4 RAM 
  • Ryzen 5 2500U processor
  • 256 GB SSD
Are you a student who hopes to game on a tight budget? It's possible with this laptop.

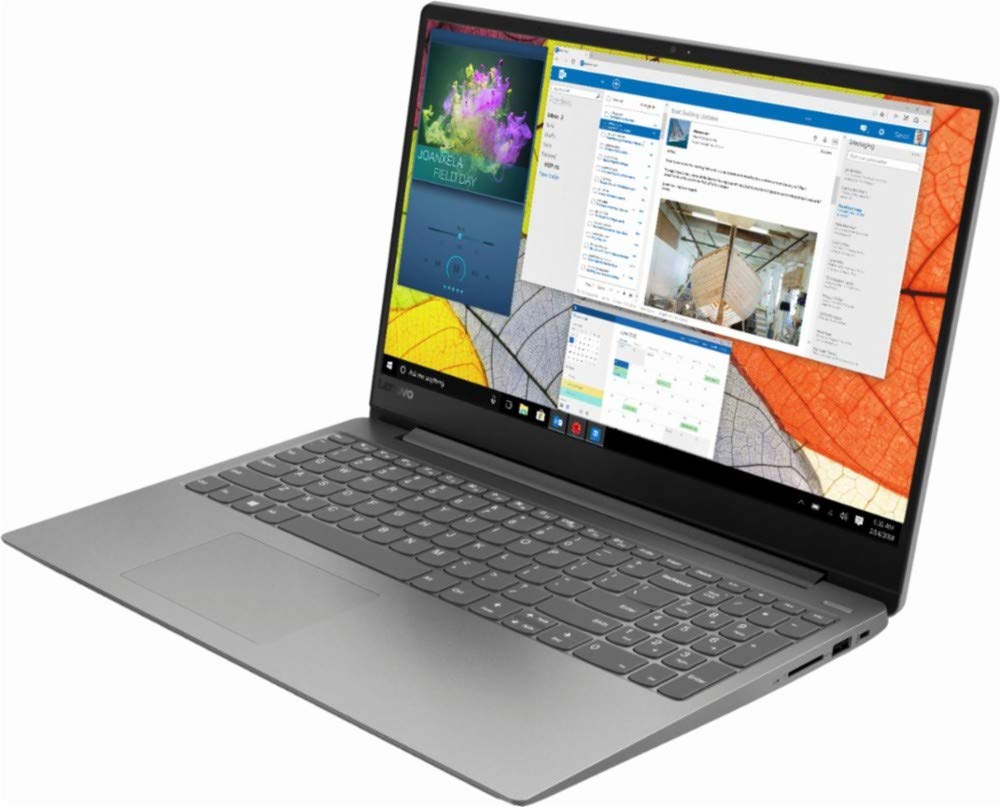
Lenovo 330S-15ARR - $410
Amazon
  • 8 GB of DDR4 RAM
  • Ryzen 5 2500U processor
  • 128 GB SSD
High-performance on a tight budget. It's also possible to game on this one, though with the tight storage requirements, I wouldn't recommend it.

ASUS X555QA - $350
Amazon

  • 8 GB of RAM
  • AMD A12-9720P processor
  • 128 GB SSD ($350) OR 512 GB ($440)
I'd get the 512 GB one for $440 if I were shopping for myself.