Showing posts with label tax. Show all posts

Tuesday, August 18, 2020

Links for August 2020

I don't normally watch a ton of YouTube videos, because there are too many time-wasters out there. But this video made a ton of great points about money, capitalism, and time.
    https://www.youtube.com/watch?v=6mRbDEtDoyA
*I'd note that the person who made this video missed one crucial element: risk tolerance. Sure, everything he says makes sense. But it doesn't make sense for just anyone to start a business. And he missed that crucial element.

Remember when everybody was panic-buying toilet paper and paper towels? This analysis provides some insight into why:

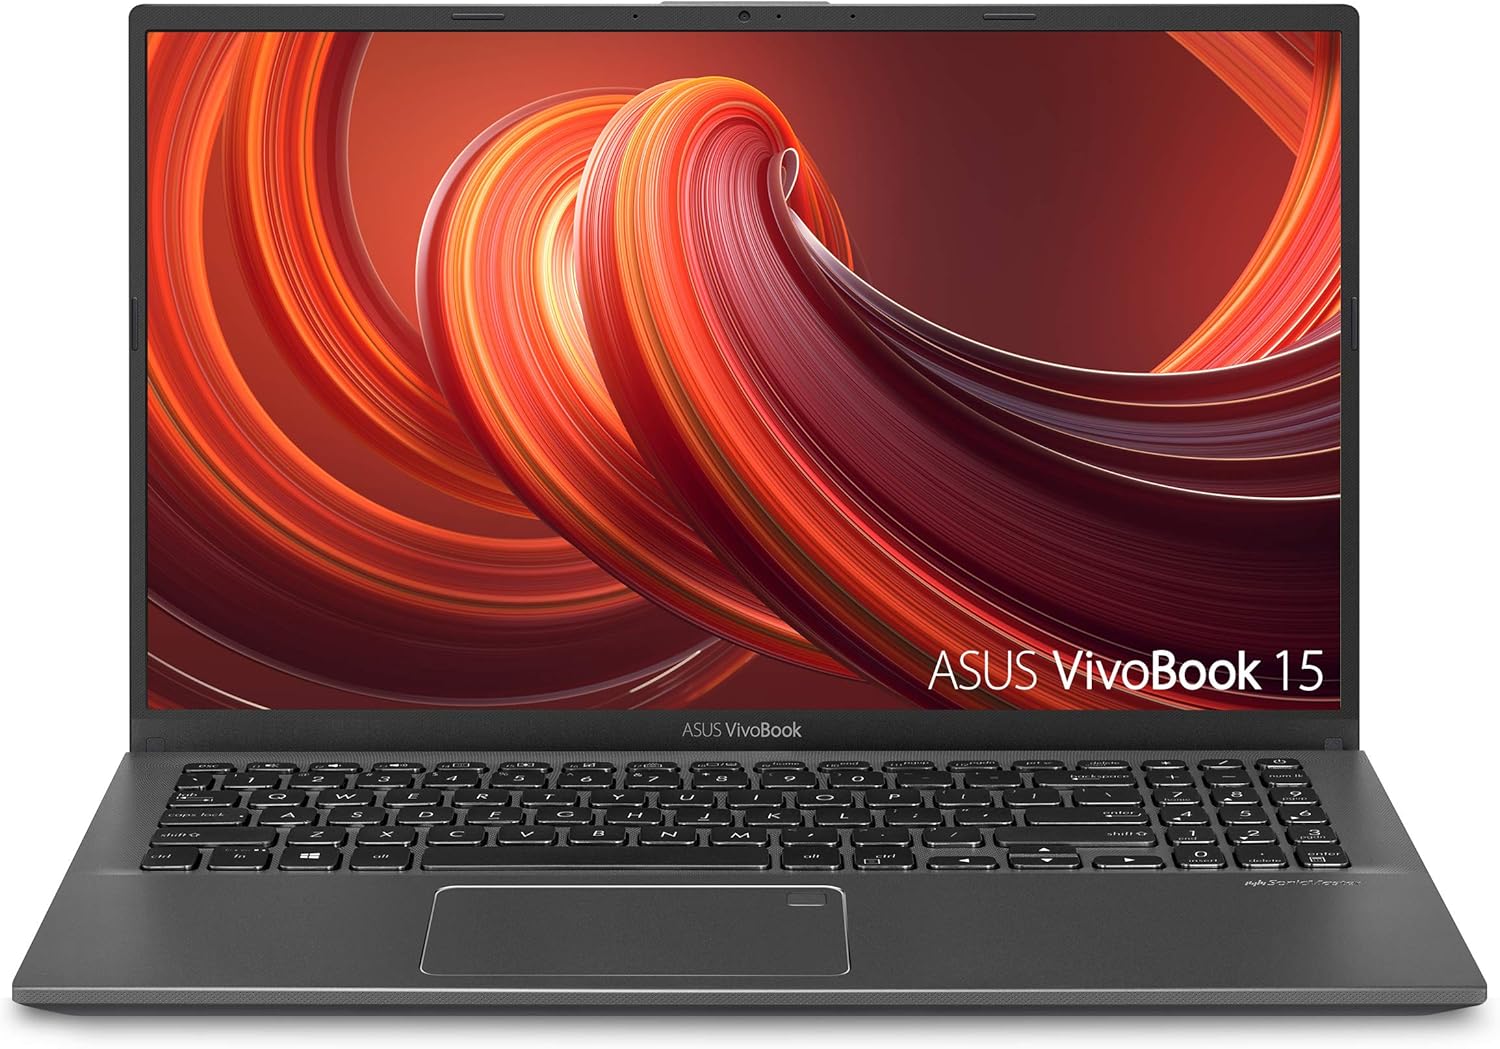
ASUS Vivobook 15 - $499
*A little light on the storage space, but it's pretty powerful for the price, and there are a number of options for extra storage.


Laws like this are exceedingly scary for homeowners:

How rich are Americans, by age group? 

Hey Americans, interested in what happens to your tax money? You might be surprised where the military ranks in this list...

A snapshot into the financial picture of "John," someone who retired in 2018 and is looking for income:

Tips to help you retire, regardless of what the economy is doing at the moment:


Steve Adcock and his wife retired early, in their thirties. He offers some advice to help the rest of us retire, as well:

Along similar lines as the above:

For some perspective on the REAL point of having money:

This post makes an important point about the power of emotions:

Scared to invest? Don't be. Here's why:

The best Vanguard funds:

Be on guard against financial abuse:

Entrepreneurship isn't necessarily all it's cracked up to be:

Possibly the single most succinct summary of the FIRE movement:

How much money do Americans think it takes to be financially comfortable? And how has COVID-19 changed that?

How should you invest? Ty of CampF.I.R.E. Finance describes one solid approach—index and chill:

Wednesday, May 13, 2020

Are Roth IRAs a rip-off?

Roth IRAs vs. traditional IRAs—What's the advantage?

A while back, I had a brief debate with Financial Samurai in the comment section of one of his articles. His position was that Roth IRAs are a rip-off. I disagreed.

I like Financial Samurai, and he has a ton of great info on his website! But sometimes, two people see things differently—the classic "reasonable people may disagree" argument. I believe that's what's happening here.


List, Demolition, Spiral Notebook, Rip, Torn, Tear

So I'll try to explain why I hold my position on the matter, using extensive quotes from the original page at https://www.financialsamurai.com/disadvantages-of-the-roth-ira-not-all-is-what-it-seems/#comment-343071

Sam: "So you think the government sucks, and you don't count on SS benefits, yet you are willing to pay more taxes up front? I don't understand the inconsistency."

Me: "There is no inconsistency."

Roth IRAs aren't a scheme to take your money. They simply give you the option to pay taxes now, or pay them later. Let me spell it out:

"You think the gov. is awful with money? [It is.] -> The gov. is going to have to pay the piper eventually. Since the gov. gets its money from taxes, that means that tax rates will be raised on everyone, across the board. I'm not talking 2019, or 2022, or 2025. I'm talking 2040 or 2050.

"If, like some people, you plan to 'work'—generate income—for as long as possible, you might well be in a higher income bracket AFTER "retirement" than you were at the beginning of your career."

-Financial Advice for Young Professionals illustrates the mathematical equivalence between a Roth IRA and a Traditional IRA, with the comment shown below:


Let’s say you’re in the 25% tax bracket. If you contribute 5,000 to a Roth IRA that is the same as contributing $6,666,67(not $5k) to a 401k. So after 10 years, both get a 5% return.
Roth: 5000*(1+.05)^10 = 8,144.47
401k: 6,666.67(1+.05)^10 = $10,859.30*(1-.25) = 8,144.47
The amounts are exactly the same after the 401k is taxed 25%. Now where I argue for a Roth is that how do you know what this 25% will go up or down. There are two factors that affect this: gov. tax rates and your future income. Both of which I guarantee you cannot predict with 100% certainty. And when you can’t predict something with certainty, I like to diversify. Which is what a Roth IRA does.
What if Sam has 3 kids and they each have 3 kids and now he has 9 grandchildren living in CA? Would he trade being away from his family for saving 10% on taxes? Hard to say :)
Me: "So, bottom line:

1) You pay the taxes now, and let that money grow. Once you're 59 and 1/2 years old, you can take the money out tax-free.

OR

2) You invest now, pre-tax, and pray that the gov. doesn't raise taxes on withdrawals 30 years in the future, or that your tax bracket in retirement is lower than your tax bracket is right now.

"Either way, you're still paying taxes on the investments in your IRA! Choosing option 1) amounts to a bet that you'll live to at least 60 years old, you won't need the money before then, and that the government will eventually have to raise taxes to bail it out of its own foolhardiness.

"Option 1) gives you certainty: you KNOW how much tax you'll pay. In 2060, I have no idea how much tax I'll pay on my forced distributions from a Traditional IRA, 401(k), etc! So Option 2) is less desirable from that standpoint.

If you pay 25% in taxes now, and you think you'll have to pay MORE than 25% in taxes in 2060, then choose a Roth IRA.

If you pay 25% in taxes now, and think you'll have to pay LESS than 25% in taxes in 2060, choose a traditional IRA."

So, to wrap things up:

Basically, whether you prefer a Roth IRA or a traditional IRA depends on what you expect the government to do regarding taxes in the future.

  • A traditional IRA means you expect your taxes to be lower in the future (either because your income will be reduced or because the government will lower your tax rate). Therefore, with this assumption, you'd rather pay later.
     
  • A Roth IRA means you expect your tax rate to be higher in the future, so you'd rather pay now.
So are Roth IRAs a rip-off? As Betteridge's Law suggests, the answer is "no." Whichever option you prefer depends on your situation. Choose wisely!


***
Support the Froogal Stoodent blog by checking out these laptops or these headphones;
anything you buy will generate a small commission—at no cost to you! Thanks!

Monday, October 20, 2014

Tax breaks for college grads

In a post on the helpful TwoCents blog at Lifehacker (twocents.lifehacker.com), Kristin Wong shares a couple ways to get some tax relief. For example, if you're paying interest on your student loan, you're eligible for up to a $2500 tax credit, based on your income and marital status.

If you've already graduated, this is a good way to help ease the burden of your student loan payments. As always, however, I promote living the 'broke college student lifestyle' that Kristin mentions in this article, even if you don't have to.

A link to her article is here: http://twocents.lifehacker.com/common-tax-breaks-available-for-recent-college-grads-1648308796